The full equipment write-off is back. Here's what it means before Dec. 31
Published · 3 min read
If you're weighing a late-season equipment buy, the tax math is a lot friendlier than it was a couple of years ago. The One Big Beautiful Bill Act, signed in July 2025, brought back 100% bonus depreciation, and made it permanent, for qualified property acquired and placed in service after Jan. 19, 2025, according to IRS Notice 2026-11. That means the full cost of a qualifying machine can come off in year one instead of being spread out. For the couple of years before this, that first-year write-off had been shrinking on a schedule and was headed toward nothing.
Two tools people mix up
There are two deductions doing similar jobs here, and farmers run them together all the time.
- Bonus depreciation. No dollar cap, and it applies to the full cost of qualifying equipment.
- Section 179 expensing. For tax years starting in 2026 the limit is $2,560,000, and it shrinks dollar for dollar once the equipment you place in service passes $4,090,000, per IRS Rev. Proc. 2025-32.
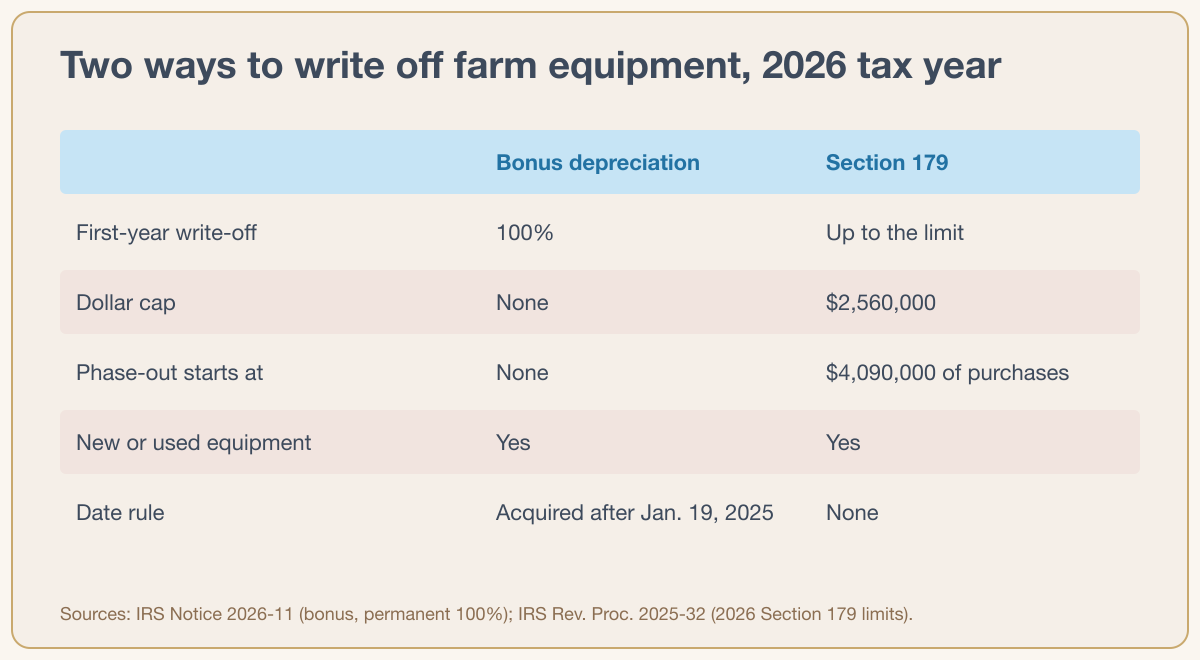
You can use both. A common move is to apply Section 179 to specific assets up to its limit, then let bonus depreciation pick up the rest. Your preparer will know which order fits your return.
"Placed in service" is the date that matters
The phrase that trips people up is placed in service. That's not the day you sign the loan or wire the deposit. It's the day the equipment is set up and ready to do its job on your operation. A combine that shows up Dec. 28 and runs is placed in service this year. One that's paid for but still sitting on the dealer's lot usually isn't. If you're counting on the deduction for this tax year, the delivery and setup date is the one to watch, not the invoice date.
Check the date on the deal, too
The 100% rate covers equipment acquired after Jan. 19, 2025, not just equipment that went to work after that date. If you signed a binding contract for a machine before then, the IRS generally treats it as acquired on the contract date, and it falls under the old, lower phase-down rate even if it showed up later. If you've got an older dealer order still coming in, ask your preparer which rate it gets. Past that, the 100% rate is permanent, so there's no countdown to beat.
A write-off isn't free money
Worth saying plainly. A big deduction lowers this year's taxable income, but when you sell or trade that machine down the road, some of that write-off can come back as income. Buying iron you don't need just to shave a tax bill is how an operation ends up asset-rich and cash-poor. The deduction is a good reason to time a purchase you were already going to make. It's a poor reason to invent one.
When you do buy, set the asset up in your books with its cost and its in-service date right away, while the invoice is in front of you. nxtAcre keeps a fixed-asset record for each machine and runs the depreciation schedule from it, so the figure your preparer needs in the spring is already sitting there.
The Section 179 limits are adjusted for inflation every year, so confirm the current numbers with your tax preparer before you buy.
This article is general information, not tax advice. Confirm how it applies to your farm with your tax preparer.
Questions and answers
Does used equipment qualify for bonus depreciation?
Bonus depreciation applies to qualifying equipment whether it is new or used. Confirm the specific asset with your preparer.
If I pay in December but it is delivered in January, which year do I deduct it?
Generally the year it is placed in service, meaning ready to use, not the year you paid. A machine delivered and set up in January is usually a next-year asset.
Is 100% bonus depreciation permanent?
Yes, under current law. IRS Notice 2026-11 describes it as a permanent 100% deduction for qualified property acquired and placed in service after Jan. 19, 2025. A future Congress could still change it.